August 2026 UK fixed income market roundup
Written by Luke Heritage
2nd September, 2026
August has been a pretty quiet month for UK politics compared to June or July, with significant changes in the UK executive branch taking place, stirring political confusion into markets, yet it was not a quiet month for yields. In fact, gilts spent the month leading a global selloff rather than reacting to domestic news. The 10-year crossed above 5% for the longest stretch in nearly two decades around mid-August closing at around 5.15%, whilst the 30-year pushed as high as 5.8% (close to levels last seen in 1998), closing at 5.77%. However, these increases have been seen globally, including the US and Germany hitting yield highs since 2007 and 2011, respectively.
MPC and the bank rate
Since there was no scheduled MPC meeting in August, with the eight meetings being spread out across the year and not falling in this month, the base rate remains at 3.75% (due to the 6-3 vote covered in the July edition) heading into September, making August a month of positioning rather than fresh votes. Market pricing has priced in 4 basis points as of late August meaning the market estimates a 4/25 or 16% chance of interest rates being hiked in the next meeting 17th September suggesting a modest probability the committee moves at all.
Gilt yields and the curve
The 10-year gilt yield's path through August is the clearest data point, moving from 4.95% to 5.14%, climbing 19 basis points over four weeks. The two-year gilt rose from 4.32% to 4.38% by month-end, and the 30-year closed at 5.77% with little change from its 5.785% close, suggesting most of the curve movement occurred at the front rather than the long end.
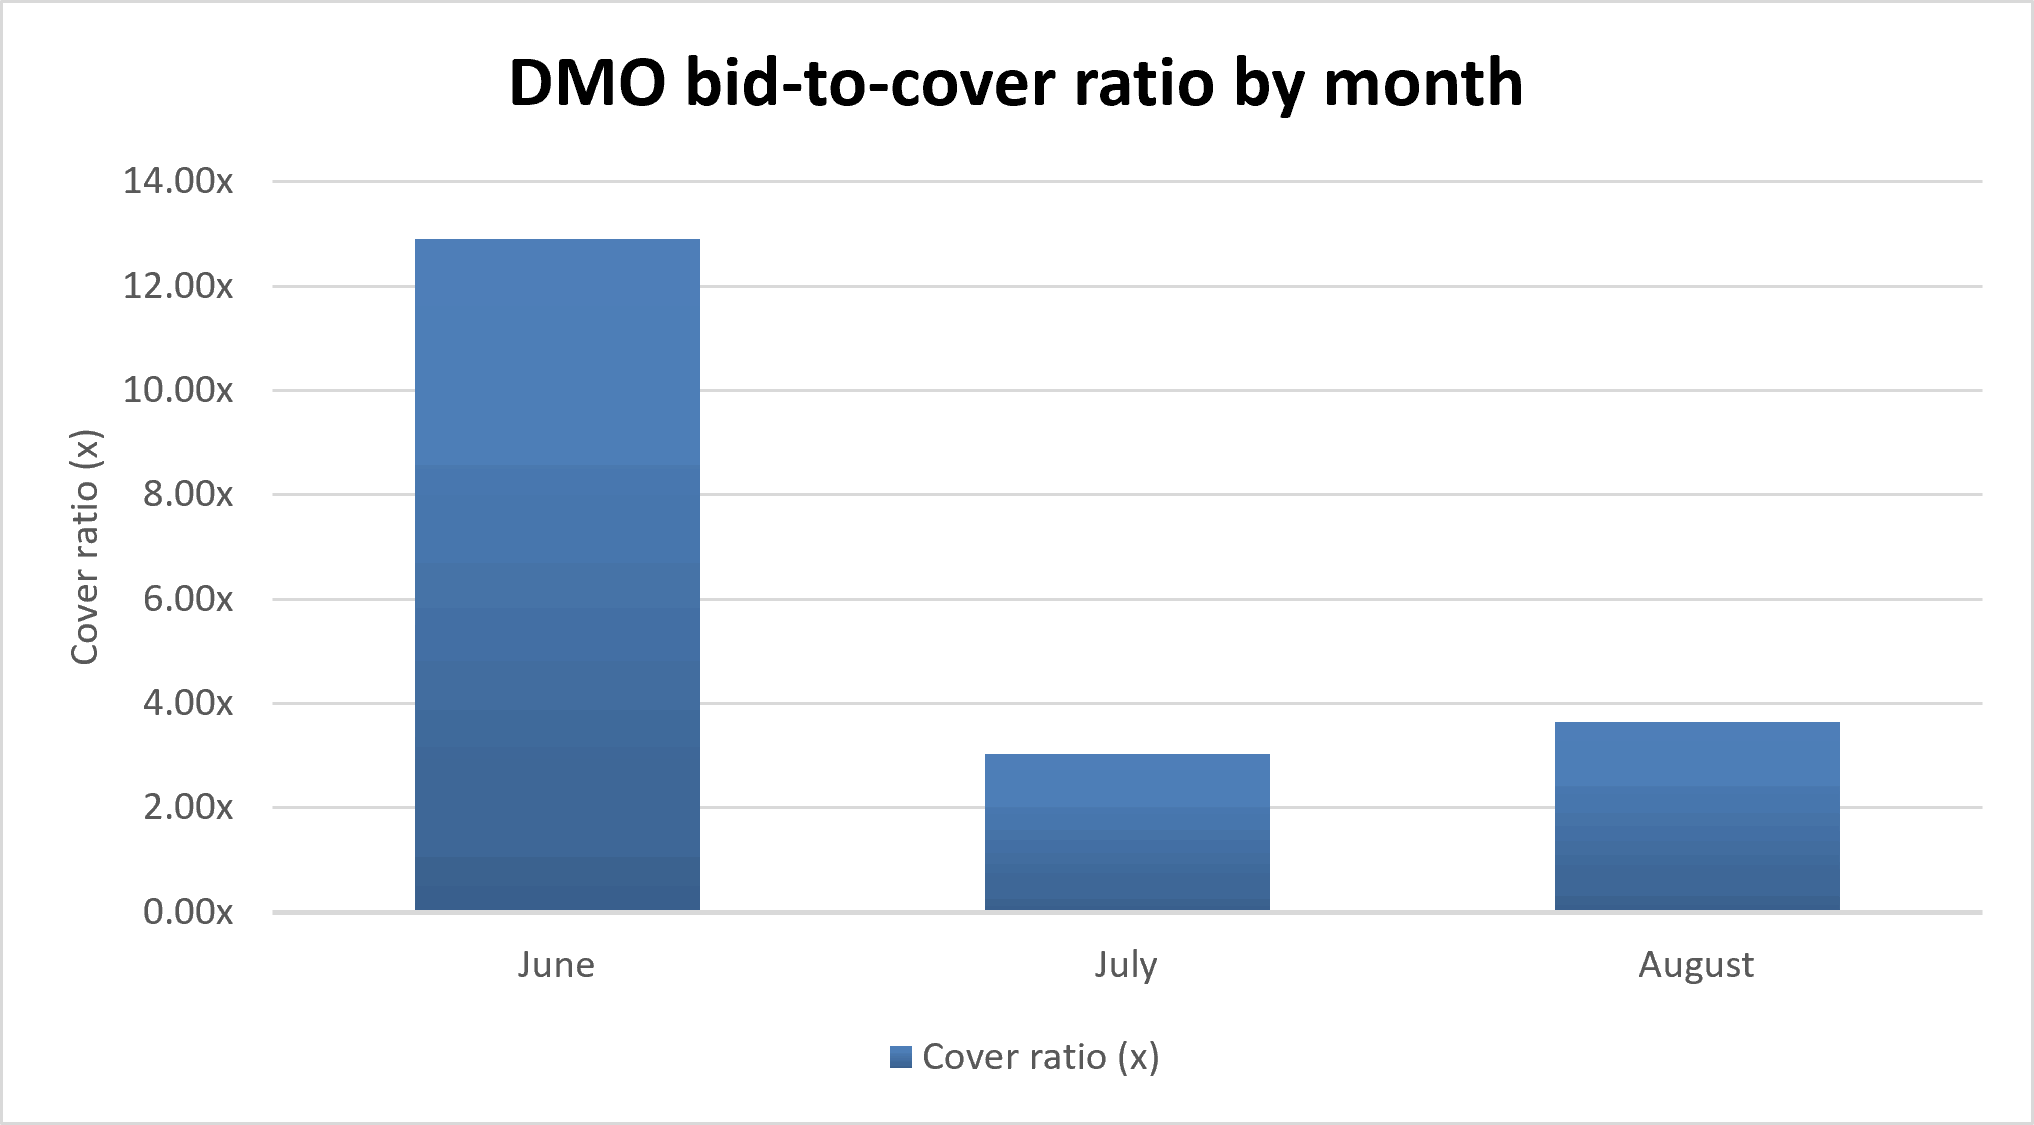
The event of the month was the DMO's syndicated auction of the 4.875% Treasury Gilt 2036 on 18th August, with total bids of almost £15bn, generating a bid-to-cover ratio of 3.65x at an average accepted yield of 5.156% and lowest price of £97.828. The tail between the lowest and average accepted yields however, was only 0.1 basis points, which indicates a well-received action produced by the gilt market, and a clear signal that August's yield rise has not weakened any demand for UK government debt. This continues to be strong just as in previous months as seen in the graph below.
What is driving the market
I would say there were three main points that defined the gilt market for August, with the first one matching global trends rather than reactions to domestic events with a synchronised major bond sell off, driven by persistent inflation and substantial national debts in countries such as the UK, US and eurozone governments meaning there is increased competition from the corporate bond market. A piece by Bloomberg highlights that gilts specifically led this global selloff as traders played "catch up" on UK-specific fiscal and inflation risk relative to its peers, thus meaning the problem of rising gilts may be global but not imported. Next, it is clear that the geopolitical situation is not progressing as expected, with reports around 18th August indicating that President Trump had declined to extend a 60-day ceasefire covering the Iranian conflict, reigniting the energy risk premium that has pushed yields higher throughout the year. Lastly, a speech by Kevin Warsh from across the Atlantic, including words such as inflation is running too high and that the Fed has work to do, naturally pushed treasuries higher, leading to a close correlation with gilts, typically shorter-maturity gilts, as they are most responsive to hawkish speculation.
Final comments
The gilt market in August mostly moved on global cues, although evidence suggests the UK has spearheaded this global trend, with the biggest moves seen on shorter-maturity bonds. However, a continuation of robust demand and a high bid-to-cover ratio indicates strong ongoing demand for gilts, with the September 17th MPC decision and any further updates in Iran looking to be the two most important things in the market looking at the weeks ahead.
Sources
Babypips "Global Bond Yields Spike to Multi-Decade Highs", 18 August 2026
Bank of England July 2026 Monetary Policy Summary and Minutes
Bloomberg "Gilts Lead Global Bond Selloff as Traders Play Catch Up", 1 September 2026
Federal Reserve Chairman Warsh's Jackson Hole keynote remarks, 28 August 2026
Investing.com "UK sells £4 billion of 10-year gilts at 5.156% yield"
Trading Economics UK 10 Year Bond Yield
Trading Economics UK 2 Year Bond Yield
UK Debt Management Office 11 August 2026 pre-auction press notice